 By
Palo Alto Networks stock has slumped in the past few weeks, moving from a high of $432 in September to the current $309, which coincides with the 200-day moving average. It has slumped by nearly 30%, mirroring the performance of top software companies, including CrowdStrike and Zscaler.
Palo Alto Networks earnings are coming up
PANW stock has slumped in the past few months as investors booked profits despite the ongoing revenue and profit growth. The most recent earnings showed that its revenue rose by 34% to $3.4 billion in the fourth quarter. Most notably, the ARR jumped by 63% to $9.1 billion, while its remaining performance obligations rose to over $21.2 billion.
Palo Alto Networks’ business has done well because of the organic demand of its products. At the same time, the company’s growth is also due to its $25 billion acquisition of CyberArk. Its business will likely continue growing demand for cybersecurity amid the ongoing artificial intelligence trends.
According to Gartner, the cost of securing AI is expected to jump to $4.8 billion in 2027, up by over 68% from a year earlier. The report said:
“This is compounded by growing vulnerabilities and supply chain attacks involving third-party and open-source software in AI projects. Without adequate security and visibility controls, enterprise AI initiatives face a high risk of failure.”
The next key catalyst for Palo Alto Networks stock will be its earnings report that comes out on Wednesday. Analysts expect the upcoming report will show that its revenue growth continued in the first fiscal quarter. The average estimate is that its revenue jumped by 33% to over $3.31 billion. Its earnings-per-share is expected to come in at 97 cents, up modestly from 93 cents in the same period last year.
Valuation concerns remain
One of the main risks that Palo Alto Networks faces is that it is a highly overvalued company. The forward price-to-earnings ratio stands at 74, much higher than the S&P 500 Index’s 18. The multiple is also much higher than the sector median of 18, and the five-year average of 59.
Palo Alto Networks’ forward price-to-earnings-to-growth ratio of 4.23 is also higher than the sector median of 1.05. The company’s Rule-of-40 multiple is also below 40. Its forward revenue growth is about 33, while the profit margin is 2.67%.
Analysts have maintained a bullish outlook for PANW stock. Citigroup analysts hiked the target from $410 to $440, while Wells Fargo boosted it from $475 to $525. Other analysts who have a bullish outlook for the company are Yorkville Ives, KeyCorp, and Cantor Fitzgerald.
Palo Alto Networks stock technical analysis
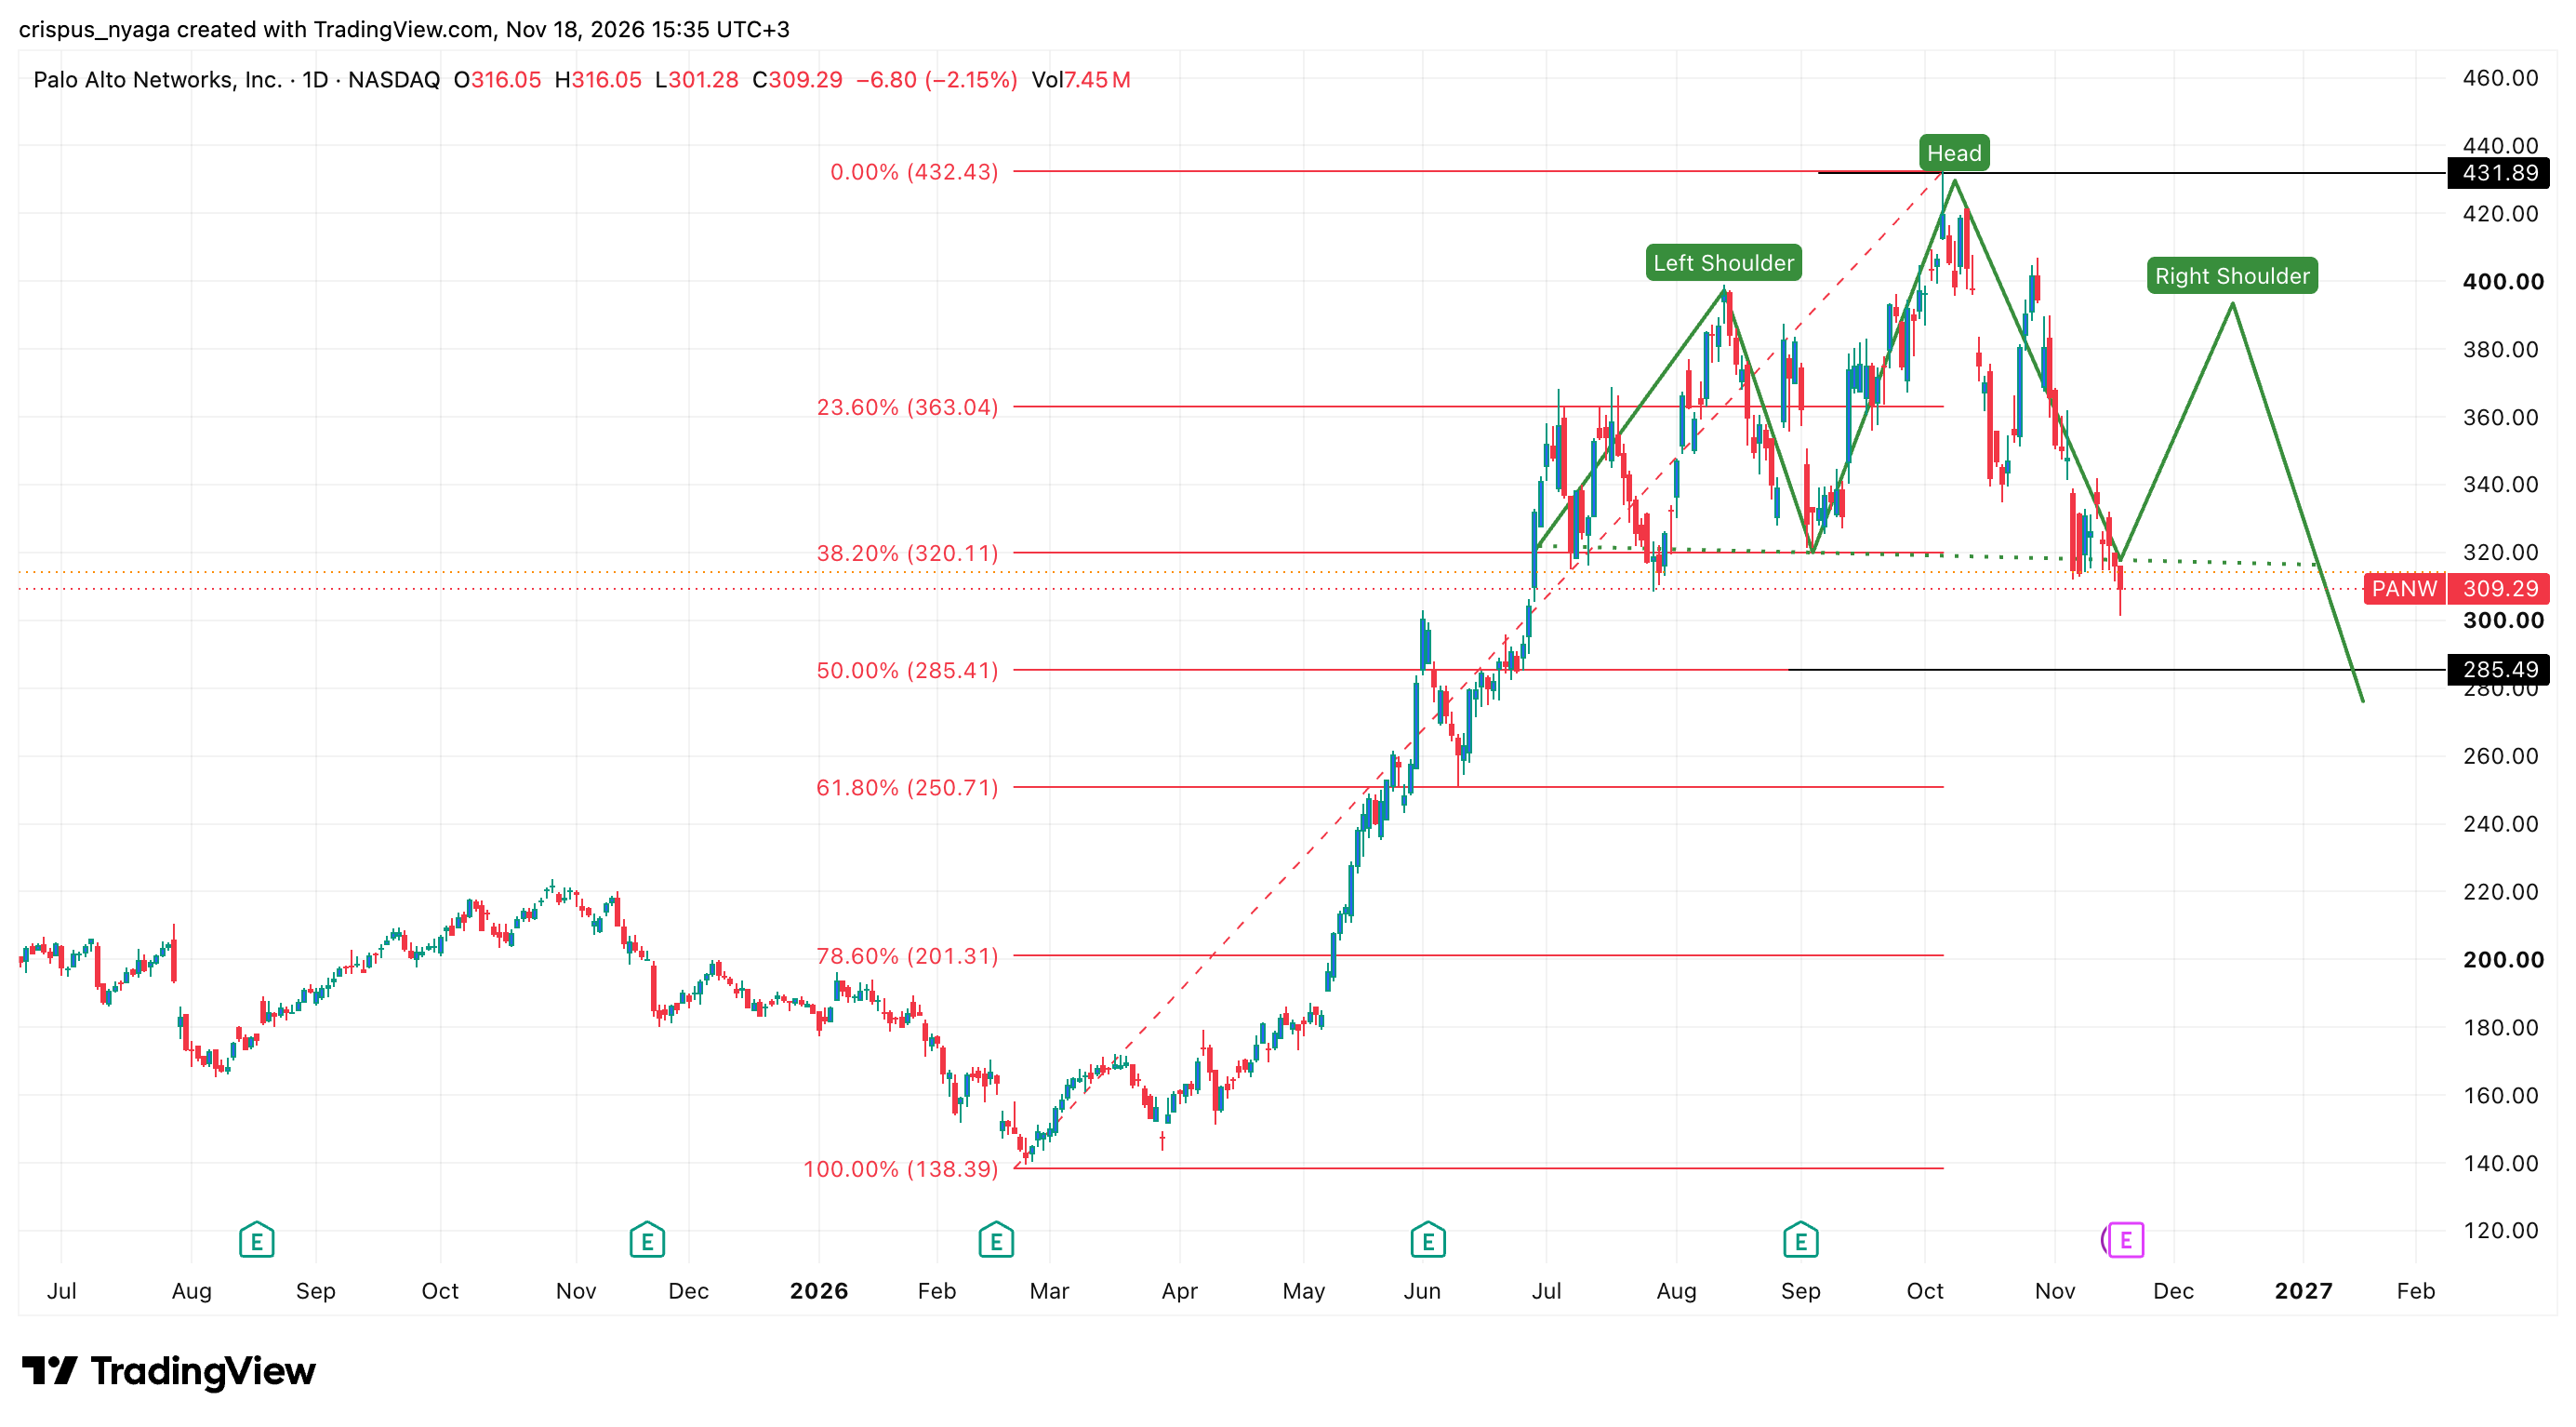
PANW stock chart | Source: TradingView
The daily chart shows that the PANW stock has jumped from $138 in February to a high of $431 in October. Since then, the stock has pulled back to the current $309.
It has dropped below the 38.2% Fibonacci Retracement level at $320. It also plunged below the 50-day moving average and the Supertrend indicator. At the same time, the Relative Strength Index (RSI) and the MACD have continued falling.
The stock has also formed a head-and-shoulders pattern, a common bearish reversal sign. It has already formed the left shoulder and the head. As such, since it has settled along the 200-day Exponential Moving Average, there is a likelihood that it will bounce back to form the right shoulder. If this happens, the stock may bounce back to $350.
On the other hand, there is a risk that the stock may drop further, potentially to the 50% Fibonacci Retracement level of $285. This target is about 10% below the current level.
The post Palo Alto Networks tests 200 EMA as a head and shoulders forms ahead of earnings appeared first on Invezz