 By
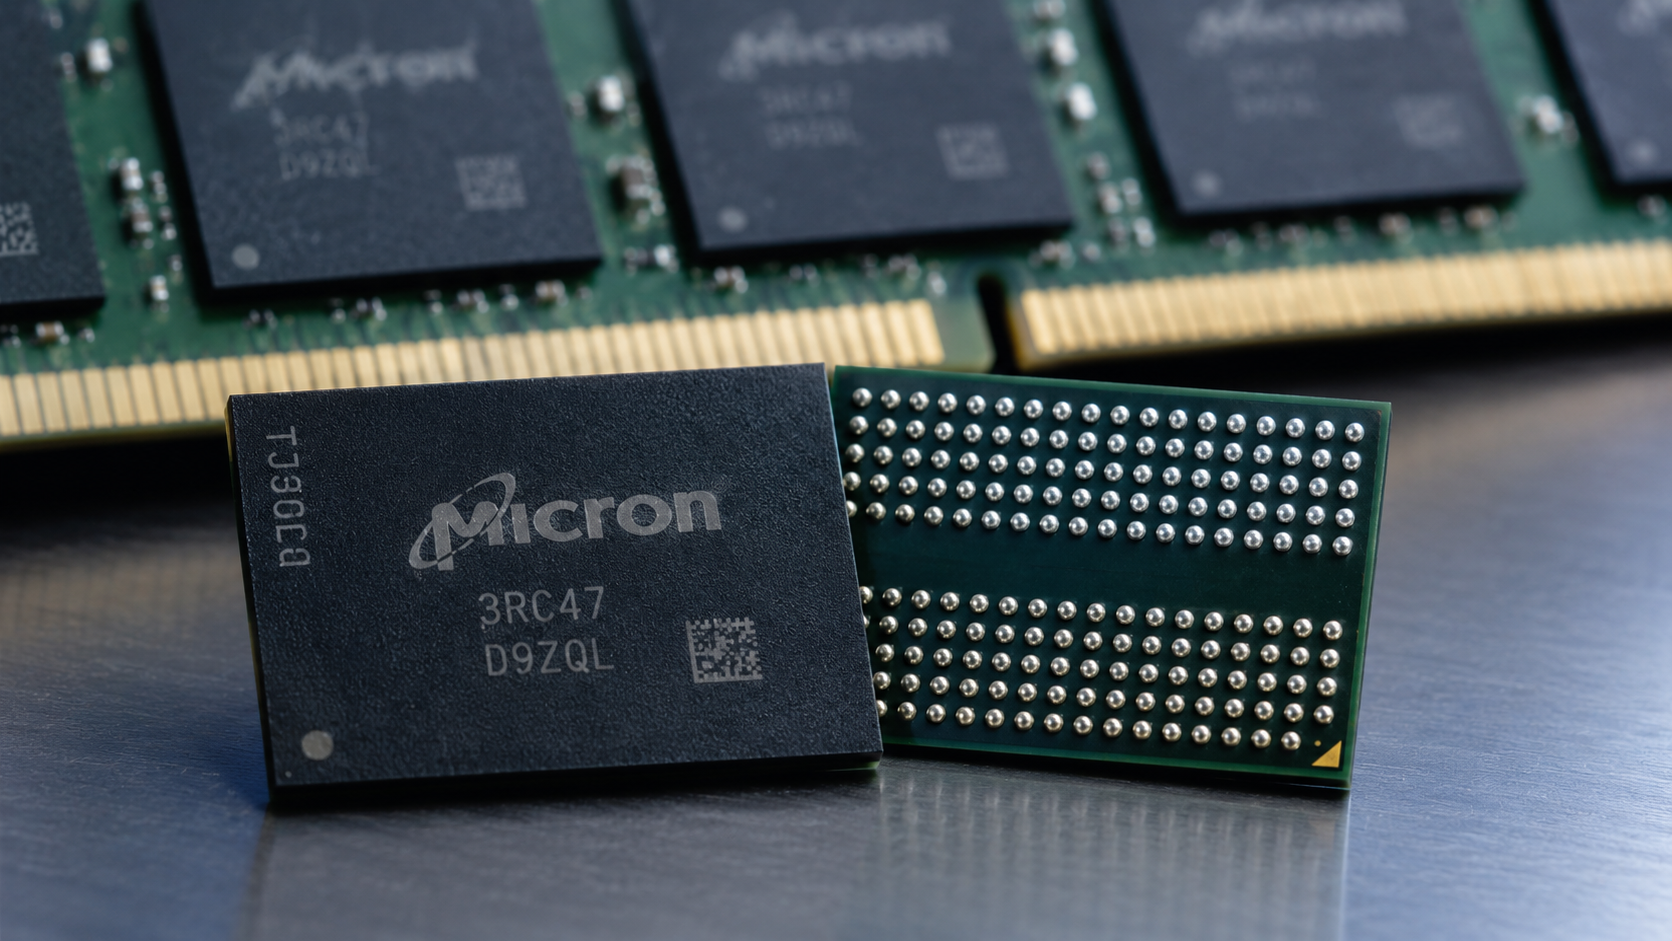
Micron Technology stock (NASDAQ: MU) has surged 226% this year, powered largely by spectacular earnings growth as booming artificial intelligence demand has driven memory-chip prices higher.
But the next phase of the rally could depend less on further earnings expansion and more on whether investors become willing to pay a higher valuation multiple for each dollar of Micron’s profits.
The stock remains unusually cheap despite its strong performance.
Micron trades at about 5.77 times estimated earnings for the next calendar year, making it the fifth-lowest valued S&P 500 component by that measure, according to Dow Jones Market Data.
TD Cowen analyst Krish Sankar believes that could change.
Micron could see a valuation rerating
Sankar said Micron shares could undergo a “rerating” as investors gain confidence that the current memory-chip cycle can remain durable even if profit margins stop expanding at their recent pace, MarketWatch reported.
His $1,600 price target is based on a price-to-earnings multiple of 9 times his 2027 earnings estimates.
That compares with Micron’s current multiple of 5.77 times and is about 73% above the stock’s Wednesday’s close.
The outlook comes as investors increasingly question how much further Micron’s margins can expand after an extraordinary period of earnings growth.
Sankar estimates the company is about 80% through its typical 18-month margin-expansion cycle.
That could mean earnings estimates may not rise as rapidly in the near term as they have recently.
Micron’s latest results demonstrate just how powerful the current cycle has been.
With memory-chip prices elevated, earnings per share jumped 1,215% in its most recently reported quarter.
AI demand changes the memory cycle
Sankar nevertheless sees a potential scenario in which earnings decline from peak levels while “the stock keeps grinding higher.”
The reason is his expectation that investors will become increasingly confident that the memory cycle is “more durable than the margin path implies.”
Demand for dynamic-random-access memory, or DRAM, used extensively in AI systems, has surged as companies invest heavily in data-centre infrastructure.
That demand profile differs from previous memory cycles, when consumer electronics played a larger role.
Sankar noted that in downturns such as those in 2019 and 2022, “supply moved ahead of demand.”
This time, sustained AI-related demand could help prevent the same imbalance and provide greater visibility for memory manufacturers.
Sankar compared Micron’s potential valuation shift with steelmaker Nucor, whose multiple expanded significantly after 2022.
In that case, the driver was not simply earnings growth but “greater confidence in cycle durability and US policy support.”
US manufacturing adds another tailwind
Micron could also benefit from its position as the “only major US DRAM manufacturer,” according to Sankar.
He estimates that Micron’s US wafer production could account for roughly half of the industry’s total US capacity by the end of 2030.
That domestic manufacturing footprint could further strengthen investor confidence in the company’s longer-term demand outlook as Washington encourages semiconductor production within the United States.
The next major catalyst is Micron’s earnings report, scheduled for September 30.
Sankar expects shareholder returns to be a major focus of the earnings call and believes Micron could authorize a share-buyback programme in the low-$20 billion range.
However, the company would likely not begin repurchasing shares before December.
The post Micron stock: could a valuation rerating drive MU shares to $1,600? appeared first on Invezz