 By
Oracle stock has slumped this year and is significantly underperforming other big technology companies like Microsoft, Meta Platforms, and Cisco. It was trading at $117.90 on Wednesday, down 52% from its highest level this year, with its market capitalization falling from over $713 billion to $356 billion. While the company looks cheap, several risks could weigh on its performance.
Oracle’s business is growing, but risks remain
Oracle’s most recent financial results showed the business is doing modestly well, helped by ongoing demand for its services. Revenue jumped 30% to $19.3 billion, making Oracle one of the fastest-growing big tech companies in the industry.
The company has benefited from a surge in demand, especially from OpenAI, the creator of ChatGPT. The deal between the two companies is worth over $300 billion. In the last report, the company said that the remaining performance obligations (RPO) jumped by $209 billion to over $664 billion.
Despite this growth, Oracle faces major challenges, which help explain why its stock has tumbled this year. One key risk is OpenAI, its top partner. According to The Wall Street Journal, OpenAI’s revenue continued to grow, but its losses surged in the third quarter. As such, there is a risk on whether OpenAI will be able to honor the deal, considering that it recently failed to hit its $30 billion target.
The company has faced other challenges. For example, it recently terminated a $7 billion deal with Tencent after coming under political pressure. Microsoft has also started winding down some of its relationship with Oracle.
Meanwhile, its Project Jupiter data center in New Mexico has faced substantial challenges, especially around power. The company has already issued a force majeure notice on the project, which means it may face delays.
Most importantly, the company has continued raising capital to fund its data center rollout. Just recently, it announced that it will raise $20 billion through a combination of debt and equity. In its earnings report, the company said that its total debt has jumped to over $174 billion. Because of its risks, its bond yields have continued rising this year.
Oracle is a bargain on most metrics
There are signs that the company has become highly undervalued. Data shows that the company has a forward price-to-earnings ratio of 14.4, much lower than that of other companies. The median multiple of the technology sector is 19.8.
The same is true of the forward PEG ratio of 0.48, which is also much lower than the technology sector median of 1.09. Similarly, a discounted free cash flow (DCF) calculation by Simply Wall St shows that the fair value of the stock is $185, much higher than where it is today.The cheap multiples are because investors believe that the company has major risks ahead.
Analysts tracking the company have a bullish outlook. The average target for the stock is $249, representing a 111% jump from the current level. KeyCorp, BTIG, and HC Wainwright have a bullish outlook.
Oracle stock price technical analysis
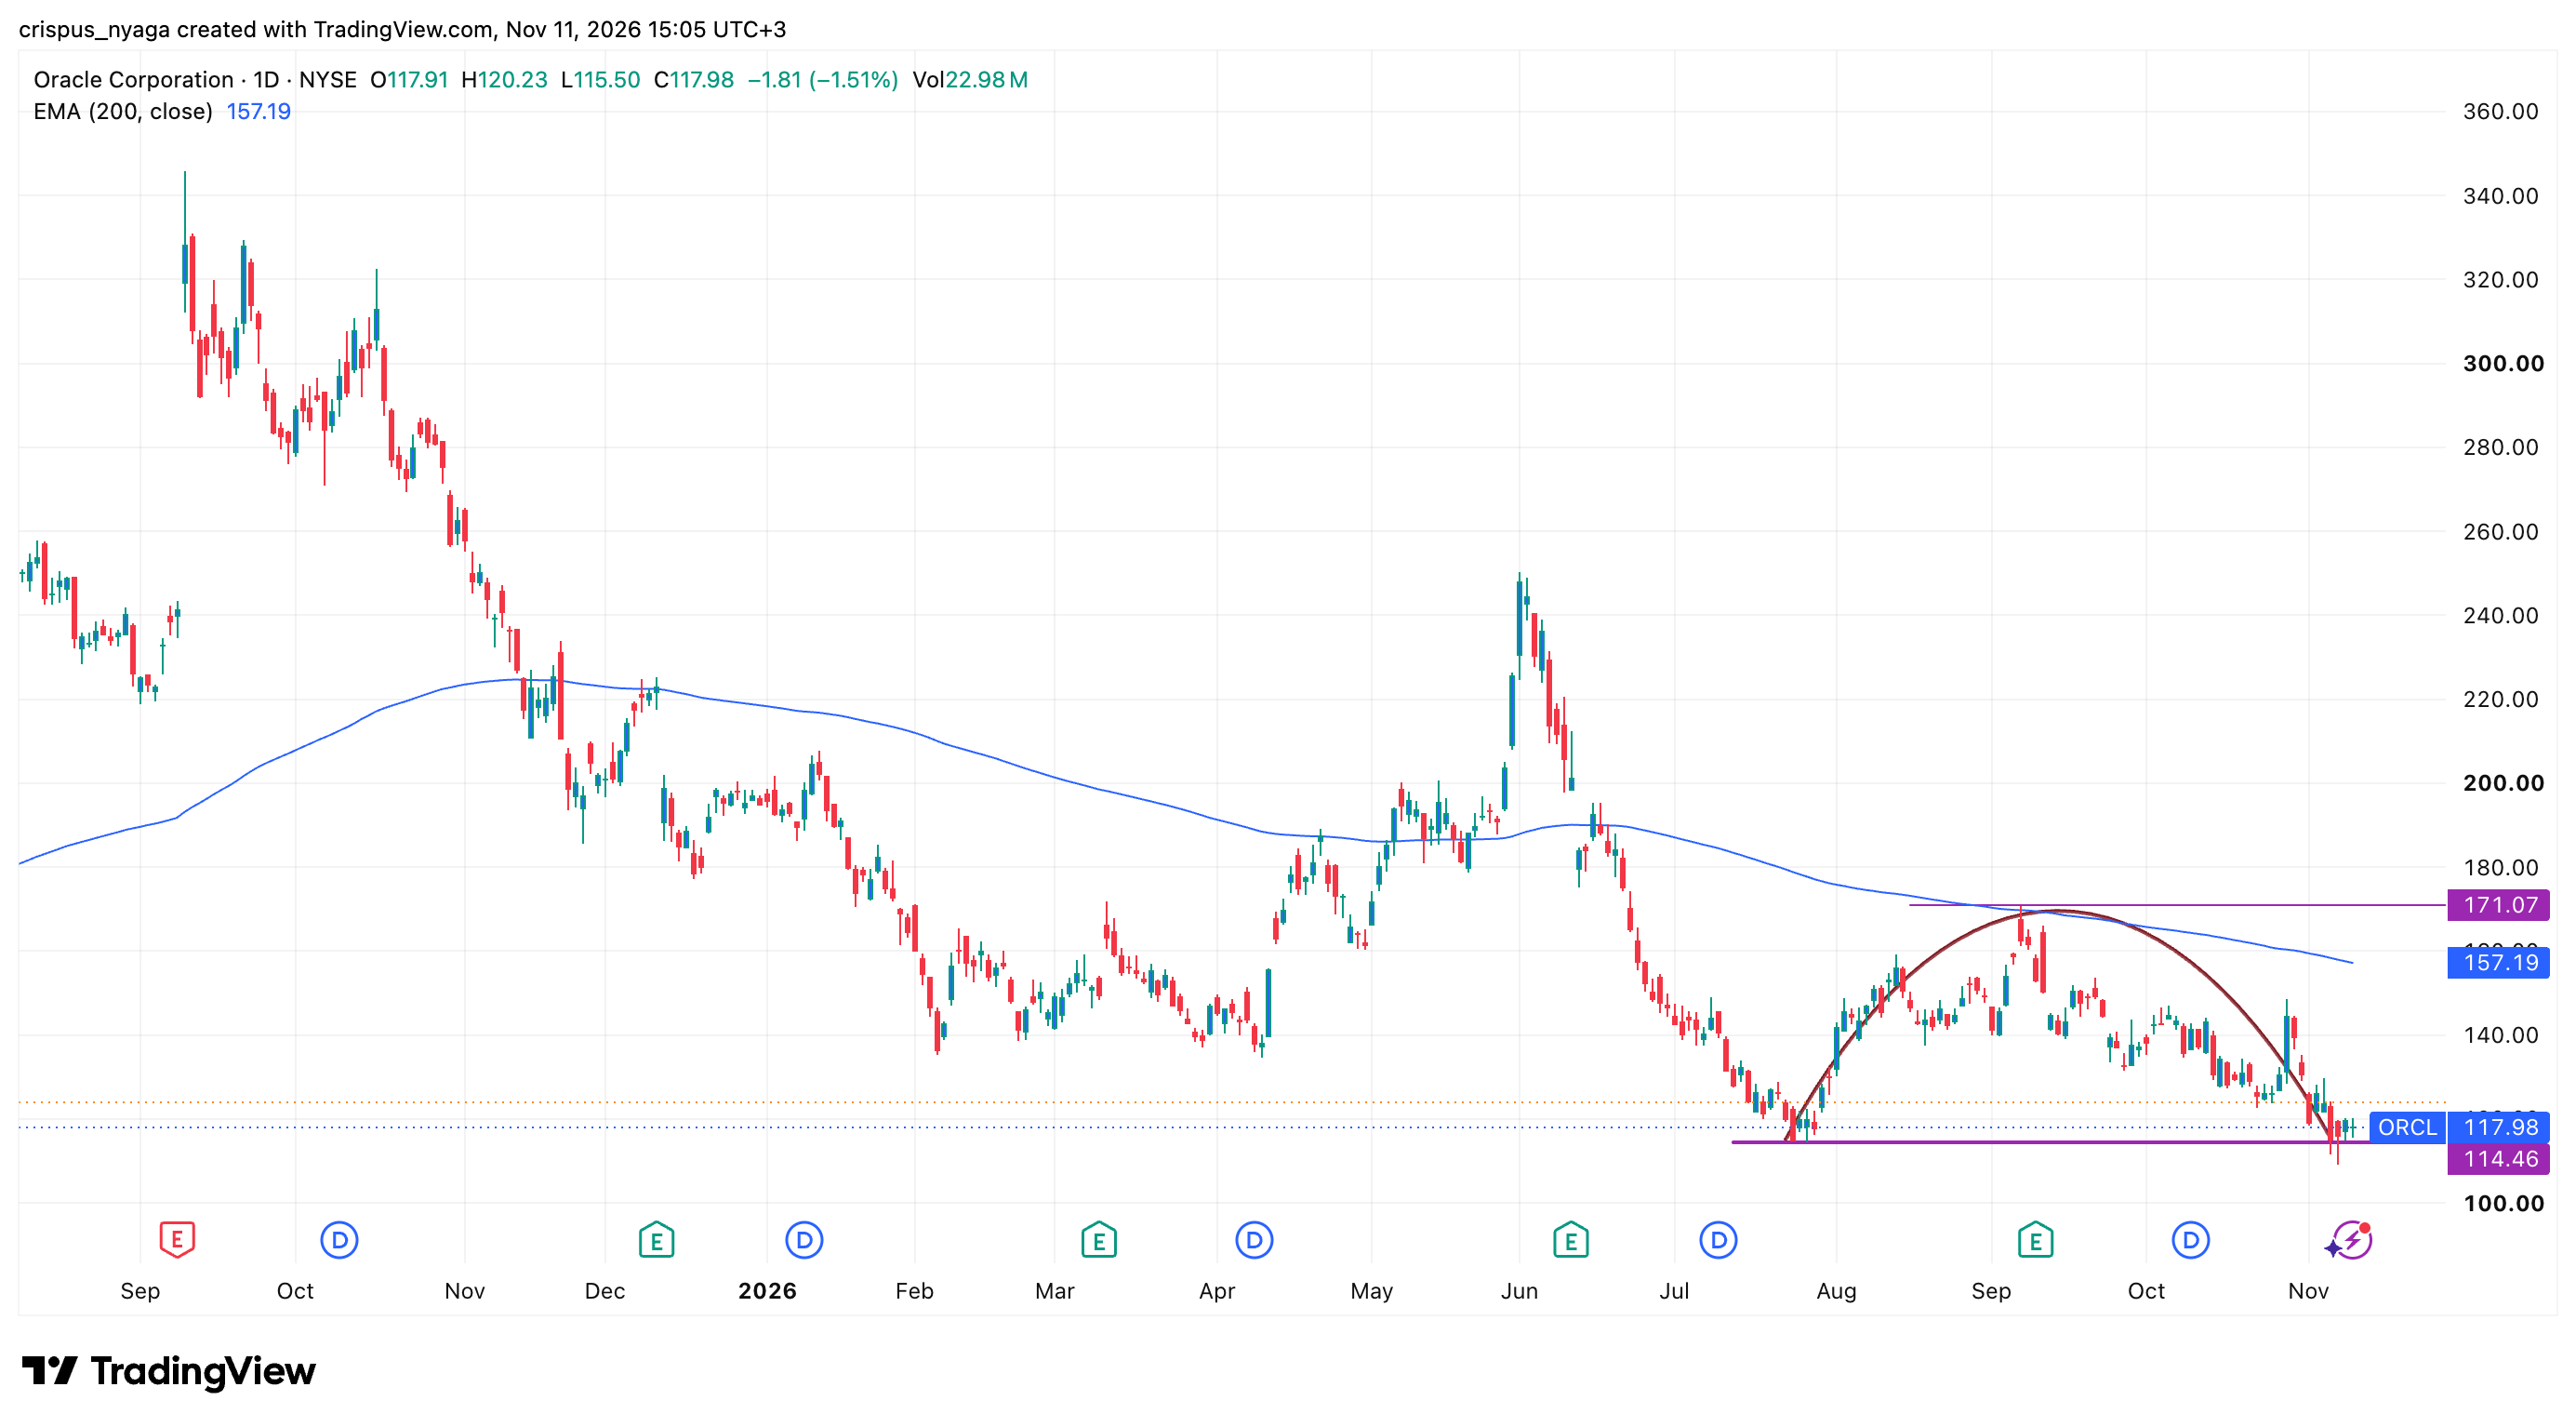
The daily chart shows that the ORCL stock has been in a downward trend in the past few months. It reached a low of $114.46, its lowest swing in July this year. It is common for stocks and other assets to rebound after hitting such an important support level.
The stock has also formed an inverted cup-and-handle pattern, which is a common continuation sign in technical analysis. It also remains below the 50-day moving average.
Therefore, while Oracle is highly undervalued, technicals suggest that the stock may continue its strong downward trend.
The post Oracle stock is a bargain, but key risks suggest it may drop to $100 and below appeared first on Invezz