 By
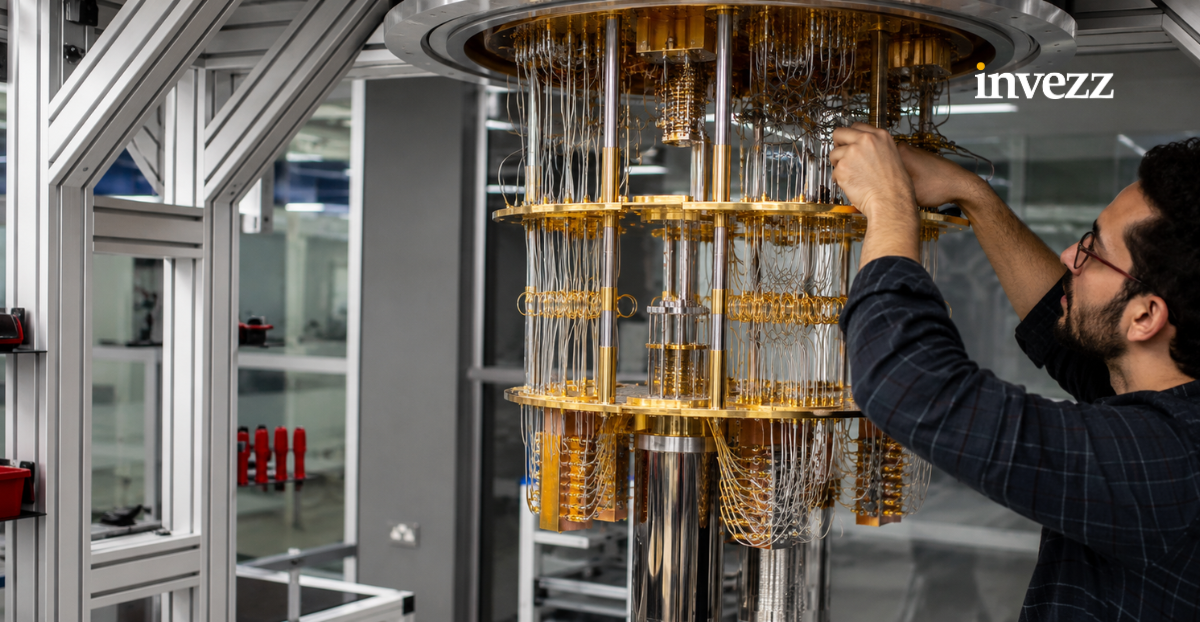
D-Wave Quantum (QBTS) shares are slipping on Tuesday morning after the company posted fiscal Q3 earnings that, at first glance, look mixed.
Revenue came in up 21% on a year-over-year basis at $4.5 million, but QBTS also reported a wider than expected loss for its third financial quarter.
Yet focusing only on earnings misses the more important development.
D-Wave’s release suggests customers are increasingly committing capital to “quantum computing projects” before the industry reaches full-scale commercialization.
In the long run, this could prove far more important than quarterly revenue fluctuations for QBTS stock that’s now trading about 60% below its price at the start of this year.
Bookings warrant buying D-Wave stock today
Most investors instinctively look at sales growth when evaluating an earnings report. In D-Wave’s case, however, the more revealing figure was bookings.
Revenue jumped to $4.5 million during the quarter, but bookings for the first nine months of 2026 surged 611% year over year to $37.4 million.
Remaining performance obligations (RPOs) – which represent contracted business expected to be recognized in future periods – printed at $38.3 million, a rather remarkable 1,221% increase.
Those numbers suggest that customers are signing larger contracts and committing to projects that may take months or years to translate into reported revenue.
For investors, this distinction matters.
Quantum computing remains an emerging industry where quarterly revenue can be volatile because a handful of contracts can heavily influence results.
A rapidly expanding pipeline of committed business often provides a clearer signal of demand than near-term sales.
All in all, the key takeaway from D-Wave’s release is that enterprise and government clients appear increasingly willing to lock in relationships today rather than wait for the tech to mature further.
Commercial adoption bodes well for QBTS shares
QBTS stock may be worth buying on the post-earnings dip also because the company continues to showcase real-world deployments rather than purely research-oriented projects.
D-Wave highlighted a second production application with Japanese telecom giant NTT DOCOMO – where its hybrid quantum technology was used to optimize network operations.
According to management, the deployment reduced peak location registration signals by “65.3%” while lowering paging signals by 7.0%.
For investors, these figures matter because they address one of the biggest questions surrounding the quantum industry: whether the technology can generate measurable economic value today.
And the significance extends beyond a single customer.
Every successful production deployment helps strengthen the argument that quantum computing is gradually evolving from a scientific milestone into a commercial tool.
That transition is often what separates speculative technologies from sustainable businesses.
While the market frequently focuses on future breakthroughs, D-Wave is attempting to build credibility by demonstrating present-day utility
How to play D-Wave after its Q3 earnings?
Perhaps the most strategically significant development from the quarter was D-Wave’s definitive agreement with the US Department of Commerce that could provide access to up to $100 million in CHIPS and Science Act funding, subject to milestone requirements.
The funding is intended to support development of both a next-generation 100,000-qubit annealing quantum computer and a 10,000-qubit gate-model quantum computer.
The importance of this announcement extends beyond the dollar amount itself.
It reflects growing government interest in quantum technology as a strategic industry alongside artificial intelligence, semiconductors, and advanced computing infrastructure.
For D-Wave investors, the agreement offers potential validation from a major government institution while also helping offset some of the capital intensity associated with developing advanced quantum systems.
That said, the quarter was not perfect.
D-Wave reported a loss of $0.13 per share, missing Wall Street expectations, even as revenue exceeded forecasts.
But the bigger picture appears to be shifting.
Investors are increasingly being asked to evaluate D-Wave not as a traditional software company, but as an infrastructure builder in a technology category that may still be years away from reaching its full commercial potential.
In that context, accelerating bookings, growing contracted revenue, expanding production deployments, and federal support may prove more consequential than a single quarter’s earnings miss.
AI disclosure: AI tools assisted with research and drafting of this piece. An Invezz editor reviewed the facts, sources and wording before publication. Any opinions or analysis are Invezz’s, not those of an automated system.
The post D-Wave investors are focused on revenue, the real story may be elsewhere appeared first on Invezz