 By
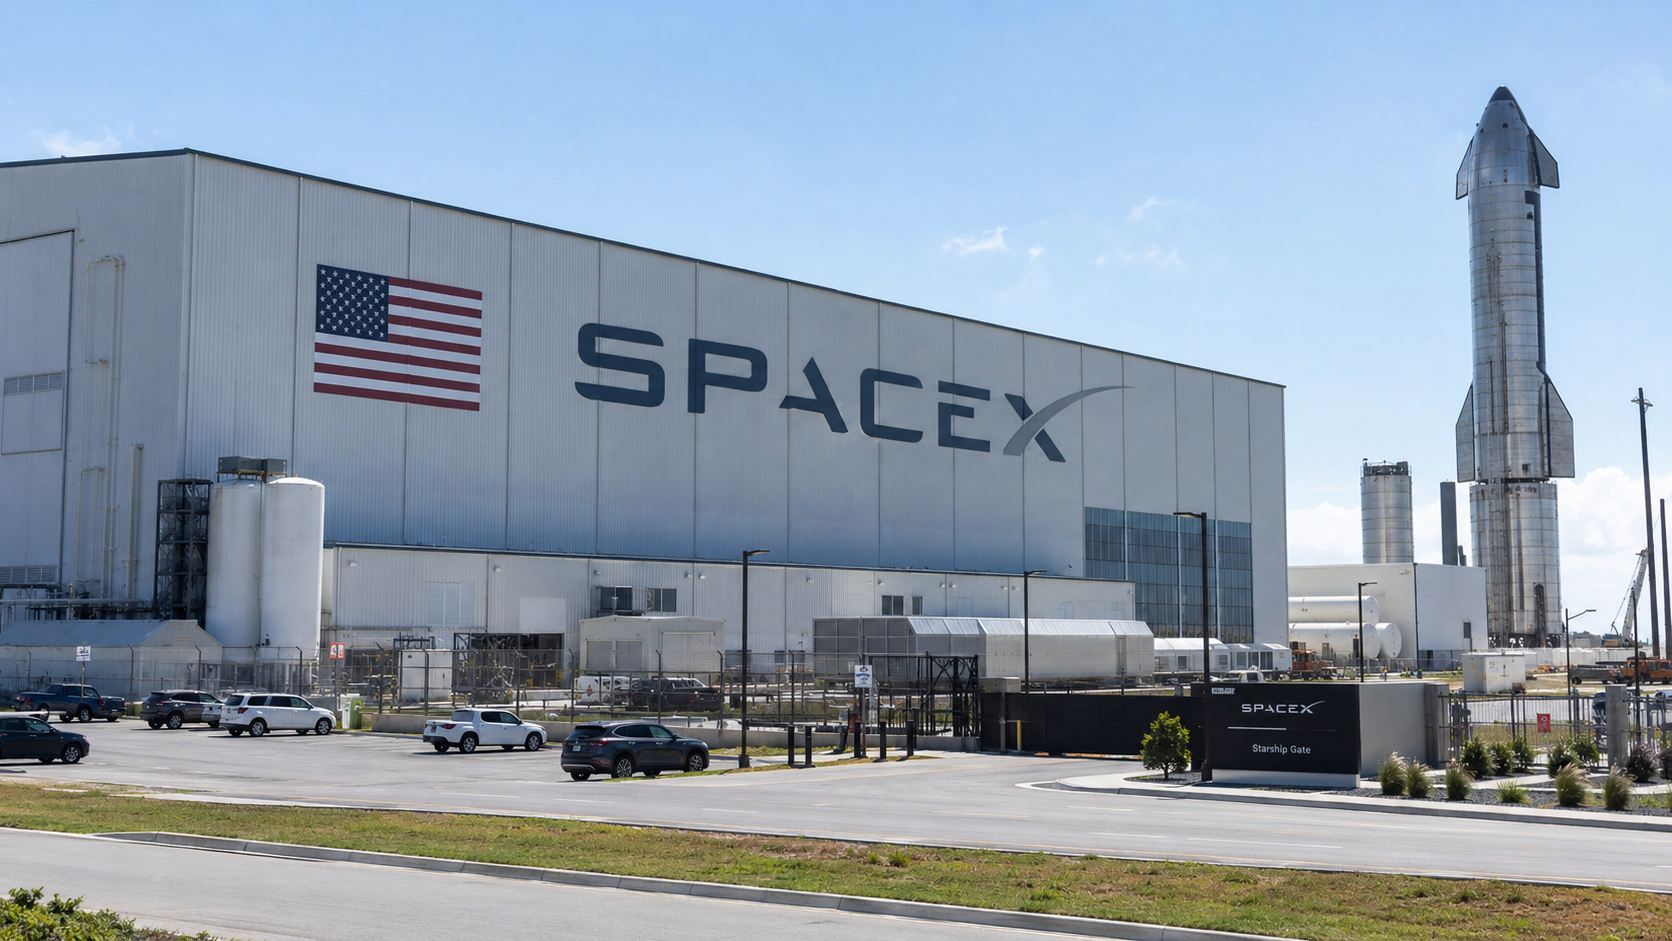
SpaceX is set to report third-quarter earnings on Tuesday, with investors looking for evidence that its rapidly expanding artificial intelligence business is generating enough revenue to justify the enormous cost of its infrastructure buildout.
The results will offer insight into whether Elon Musk’s ambitions to combine AI computing, satellite connectivity and space-based infrastructure can translate into sustainable financial returns, or whether mounting capital requirements and borrowing needs could become a growing risk.
According to FactSet data, SpaceX is expected to report earnings per share of 13 cents, compared with a loss of nine cents per share in the June quarter.
Revenue is projected to reach $12.8 billion, representing a 64% increase from the same period a year earlier.
The company reported second-quarter revenue of $7.8 billion, a net loss of $541 million and AI capital expenditure of $15.8 billion.
SpaceX stock has fallen over 8% since its IPO in June.
AI revenue grows as infrastructure spending accelerates
A significant part of the anticipated revenue growth is expected to come from SpaceX selling access to the computing resources required to develop and run AI models.
Deutsche Bank analyst Edison Yu expects AI revenue to have nearly tripled from the June quarter to approximately $6 billion, MarketWatch reported.
Yu estimates that the handful of customers SpaceX has signed to purchase AI computing capacity represent $54.5 billion in annualised run-rate revenue.
This measure extrapolates revenue over a year based on performance during a shorter period.
That figure accounts for more than half of SpaceX’s $100 billion year-end revenue target.
However, generating that revenue requires substantial investment in data centres, computing hardware and supporting infrastructure.
SpaceX must expand its capacity to accommodate both its internal AI development and external customers, while its ambitions to establish data centres in space could add another expensive dimension to the buildout.
Yu said in a client note on Monday that he estimates SpaceX spent $19 billion in capital expenditure last quarter, primarily on AI computing infrastructure.
Wall Street expects the company’s total capital expenditure to reach $67 billion by the end of the year, according to FactSet.
Borrowing needs emerge as a key risk
The scale of SpaceX’s investment plans raises questions about how the company will finance its expansion without putting pressure on its balance sheet.
One analyst has estimated that the company’s infrastructure spending could reach as much as $336 billion in 2027.
SpaceX reportedly aims to borrow $40 billion to finance Nvidia chips used in its data centres, after raising $25 billion in debt just a few months ago.
The concern is that expenditure could continue to balloon as SpaceX invests in data centres such as Colossus and AI products including Grok and its agent, Grok Bot.
Morgan Stanley analyst Adam Jonas identified financing as a major concern for investors.
“Need for additional financing remains a key overhang for sentiment, especially given the recent neocloud debt saga,” Jonas wrote in a note published on Monday.
“This is the biggest risk to our model, and we do not want to downplay it — although a hypothetical world where SpaceX cannot raise financing likely has much broader implications for the economy and the rest of an investor’s portfolio.”
Jonas expects SpaceX to issue $60 billion, $80 billion and $90 billion in debt in 2027, 2028 and 2029.
Evercore ISI expects SpaceX to exit 2026 with an annualised revenue run-rate of approximately $104 billion, with AI doing “most of the heavy lifting”.
The firm estimates capital expenditure could reach around $151 billion in 2027.
The gap between anticipated revenue and the cost of building infrastructure will be central to investors’ assessment of whether the company’s AI ambitions can produce sustainable returns.
Starlink and Starship remain central to the growth story
Beyond AI, investors will be watching the performance of Starlink, SpaceX’s satellite-internet business, and its efforts to compete more directly with traditional telecommunications companies such as AT&T and T-Mobile.
Connectivity revenue, which includes Starlink, rose 66% to $4.3 billion in the second quarter.
Earlier this month, SpaceX said it would buy some low-band spectrum, moving closer to its ambition of becoming a mobile carrier and broadening its reach beyond satellite broadband.
Investors are also looking for an update on when Starship will fly again.
The rocket is central to SpaceX’s plans to develop its various businesses, including deploying satellites and potentially supporting future space-based computing infrastructure.
SpaceX last launched the giant rocket in September, briefly sending it into orbit for the first time and deploying 26 of the company’s new satellites.
“We believe that SPCX’s unrivaled launch capabilities represent the foundational competitive advantage that enables all other parts of its business,” bullish Citi analysts led by John Godyn said in a recent note to clients, MarketWatch reported.
Tesla results put merger speculation in focus
SpaceX and Tesla are also scheduled to report third-quarter results on consecutive days this week, giving investors an opportunity to assess the financial performance of Musk’s two most valuable companies as speculation about a potential merger gathers momentum.
The results will test whether Starlink’s steady growth and Tesla’s automotive profits can help support the enormous AI spending that has become central to the merger debate.
Barclays suggested last week that a deal could be announced before Tesla’s annual meeting, with SpaceX the likelier acquirer.
Neither company nor Musk has officially committed to pursuing a transaction.
Tesla said on Monday that its annual meeting would take place on December 3.
In an all-stock transaction, Barclays estimates Musk would own approximately 37% of the combined company’s equity and control 56% of its votes.
“A SpaceX acquisition of Tesla would be cleaner as it would make it easier to deal with the China business as an asset that is dealt with separately,” Shawn Campbell, an adviser at Camelthorn Investments who owns shares in both companies, said in a Reuters report.
Tesla fuelled speculation on Thursday by unveiling a new Roadster sports car, scheduled for production in 2028, that can jump and turn over mid-air using rocket technology.
The unveiling took place at a SpaceX test site in Texas.
“Musk is blending the future of mobility together by integrating auto and rocket technology; at the very least it’s a subtle plant in investors’ minds making an engineering efficiency argument for a merger,” said Bill Birmingham, head of research at REX Financial in the Reuters report.
Birmingham said the timing of the unveiling, ahead of Tesla’s annual shareholders meeting, was no coincidence.
For investors, the immediate focus remains on whether SpaceX can convert its AI investment into durable earnings while securing the financing needed to sustain its expansion.
Its quarterly results could also provide fresh clues about how Musk intends to bring his AI, automotive, connectivity and space ambitions closer together.
The post SpaceX earnings: AI revenue, financing needs and Tesla merger talks in focus appeared first on Invezz