 By
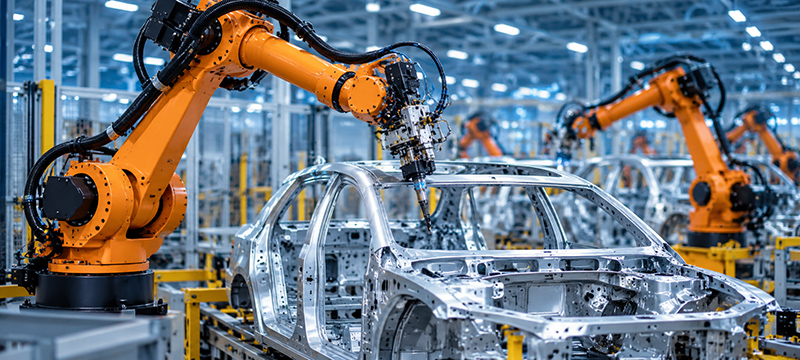
The global operational stock of industrial robots reached a record 5 million units in 2025, as factory automation continued to expand rapidly but with increasingly pronounced differences between regions.
Industrial robotics is becoming a much larger part of the connected factory landscape. As robot fleets grow, manufacturers are not simply adding more automated machines: they are managing increasingly complex environments combining robotics, machine vision, sensing, production software and connected industrial infrastructure.
New figures from the International Federation of Robotics (IFR) illustrate the scale of that shift. The global installed base of operational industrial robots increased 9% in 2025 to reach 5 million units, more than twice the level recorded seven years earlier. Factories installed more than 600,000 new robots during the year, an 11% increase compared with 2024.
China drives an increasingly uneven robotics market
The most striking aspect of the latest data is not simply the five-million-unit milestone, but how unevenly new deployments are distributed around the world.
China accounted for 59% of global robot installations in 2025. The country installed 354,000 industrial robots during the year, an increase of 20%. Chinese robot manufacturers also supplied 195,000 of those units, representing 55% of their domestic market.
That concentration gives China a very different automation trajectory from other major manufacturing economies. The United States became the world’s second-largest market for new installations in 2025, overtaking Japan, but its nearly 38,500 installations remain far below China’s volume. US deployments nevertheless increased by 12%, reaching their third-highest annual level on record.
Japan installed 36,219 robots, down 19%, while South Korea recorded around 30,000 installations, down 1%. India remains much smaller in absolute terms but continues to expand quickly: installations approached 10,500 units in 2025, up 15%, after growing at an average annual rate of 27% between 2020 and 2025.
Europe moves at a slower pace
The European picture is notably different. Germany remains Europe’s largest industrial robotics market and the fifth largest globally, accounting for 41% of EU installations in 2025. However, German installations fell 8% to fewer than 25,000 units.
Italy recorded approximately 7,800 installations, down 11%, while France returned to third place among European markets with almost 4,500 units despite an 8% decline. Spain installed roughly 4,300 robots, 15% fewer than in the previous year.
For industrial technology suppliers, this regional divergence matters. A global increase in automation does not necessarily translate into comparable deployment opportunities in every manufacturing market. Robot vendors, industrial IoT providers and system integrators increasingly face different investment cycles and automation maturity levels depending on geography.
More robots mean larger connected industrial environments
From an IoT perspective, the significance of five million operational robots extends beyond the robot market itself. Modern automated production depends increasingly on sensing, machine vision, industrial networking and software integration. The IFR specifically identifies advances in artificial intelligence, machine vision and sensing as technologies expanding the range of applications where robots can be deployed.
There is also an operational implication as robot populations expand: manufacturers have more automated assets whose availability, condition and production data need to be managed alongside the rest of the factory infrastructure. That increases the importance of integration between robotic systems and broader industrial monitoring and control environments, rather than treating robots as isolated pieces of automation equipment.
This is what makes the latest IFR figures particularly relevant to the industrial IoT ecosystem. They measure physical automation rather than connected-device shipments, but the expansion of the installed robot base creates a correspondingly larger environment in which industrial connectivity, sensors, edge computing and machine data can play a role.
The IFR expects the expansion to continue. Global installations are forecast to increase 9% to 655,000 units in 2026 and reach 806,000 units annually by 2029. The organization points to manufacturing relocation, labor shortages, demographic changes and advances in automation technology among the factors supporting longer-term demand.
For OEMs and industrial system integrators, the result is a factory landscape in which robotics and connected industrial infrastructure are becoming increasingly intertwined. Five million operational robots is therefore more than a robotics milestone: it also indicates the growing scale of the physical equipment that tomorrow’s industrial IoT architectures will need to connect, monitor and manage.
The post Five Million Industrial Robots Are Now Operating in Factories Worldwide appeared first on IoT Business News.