 By
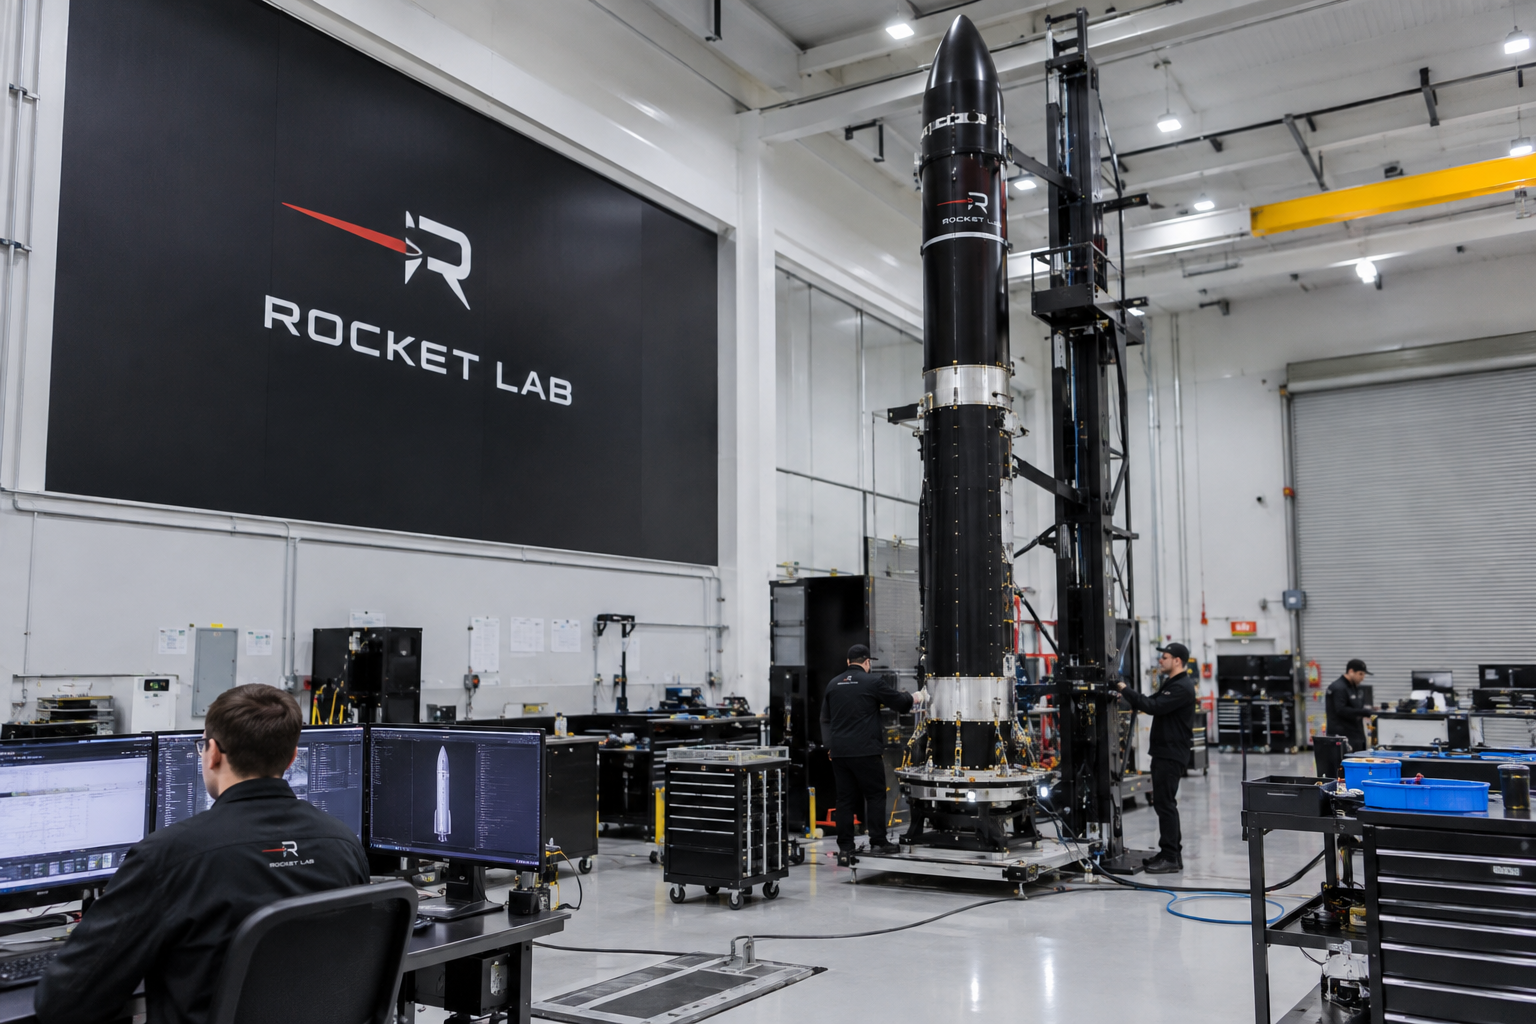
Rocket Lab shares RKLB rose over 1% during Thursday trading after the space company secured its largest commercial launch contract to date, strengthening its position in the increasingly competitive satellite-launch market.
Further, Citi also initiated coverage of Rocket Lab with a Buy rating and a $105 price target, implying about 50% upside from Wednesday’s closing price.
The company signed a multiyear agreement with Tokyo-based satellite operator Synspective for 20 additional Electron missions.
The deal takes the total number of Electron launches contracted by Synspective to 47, making it Rocket Lab’s largest customer by mission count.
Financial terms of the agreement were not disclosed.
The stock had gained over 4% in premarket trading but lost most of the gains after the market opened.
Rocket Lab expands Synspective partnership
Rocket Lab will launch 20 StriX synthetic aperture radar satellites into sun-synchronous orbit from its Launch Complex 1.
The missions are scheduled annually between 2028 and 2031 and will support Synspective’s plans to build a satellite constellation capable of imaging locations around the world within hours, regardless of whether it is day or night or whether weather conditions are favorable.
The contract provides Rocket Lab with additional visibility into future launch activity as it continues expanding its commercial and government customer base.
The company operates launch facilities in both New Zealand and the US and offers multiple rocket platforms, including Electron, Haste and the larger Neutron vehicle.
Citi sees further upside for Rocket Lab stock
The latest contract comes as Wall Street firms highlight Rocket Lab’s position in the commercial space market.
Citi initiated coverage of Rocket Lab with a Buy rating and a $105 price target, implying about 50% upside from Wednesday’s closing price.
The brokerage said Rocket Lab is one of only a few companies “on the planet” providing regular commercial access to orbit.
Citi also highlighted the company’s established Electron rocket and described Rocket Lab shares as a “core holding for space bulls.”
Cantor Fitzgerald earlier this week reiterated its Overweight rating and $122 price target.
The firm pointed to Rocket Lab’s track record of successful launches and its diversified business across commercial and government customers and domestic and international markets.
Cantor identified the first launch of Rocket Lab’s Neutron rocket and the closing of the company’s Iridium acquisition as potential catalysts.
Neutron remains under development and testing, with its first launch date yet to be confirmed. Cantor has previously described the vehicle as a potential competitor to SpaceX’s Falcon 9.
Revenue and backlog continue to grow
Rocket Lab’s operational momentum has also been reflected in its financial results.
Revenue jumped 62% year over year to $234 million in the second quarter, while the company’s backlog surged 137% to a record $2.36 billion.
Rocket Lab secured $437 million of contracts during the quarter across its Electron, HASTE and Neutron programs.
The company is targeting the start of Neutron launches either this year or early next year, although the timing remains dependent on development and testing progress.
Rocket Lab shares are still down more than 8% this year despite gaining about 11% over the past month.
Analysts expect the company’s growth to accelerate.
The average forecast calls for annual revenue to rise about 60% to $958 million this year and reach approximately $1.36 billion next year.
The latest Synspective agreement adds another long-term source of launch demand as Rocket Lab seeks to convert its growing backlog and launch track record into sustained revenue growth.
The post Rocket Lab shares rise on contract with Synspective: why Citi sees a 50% upside appeared first on Invezz